

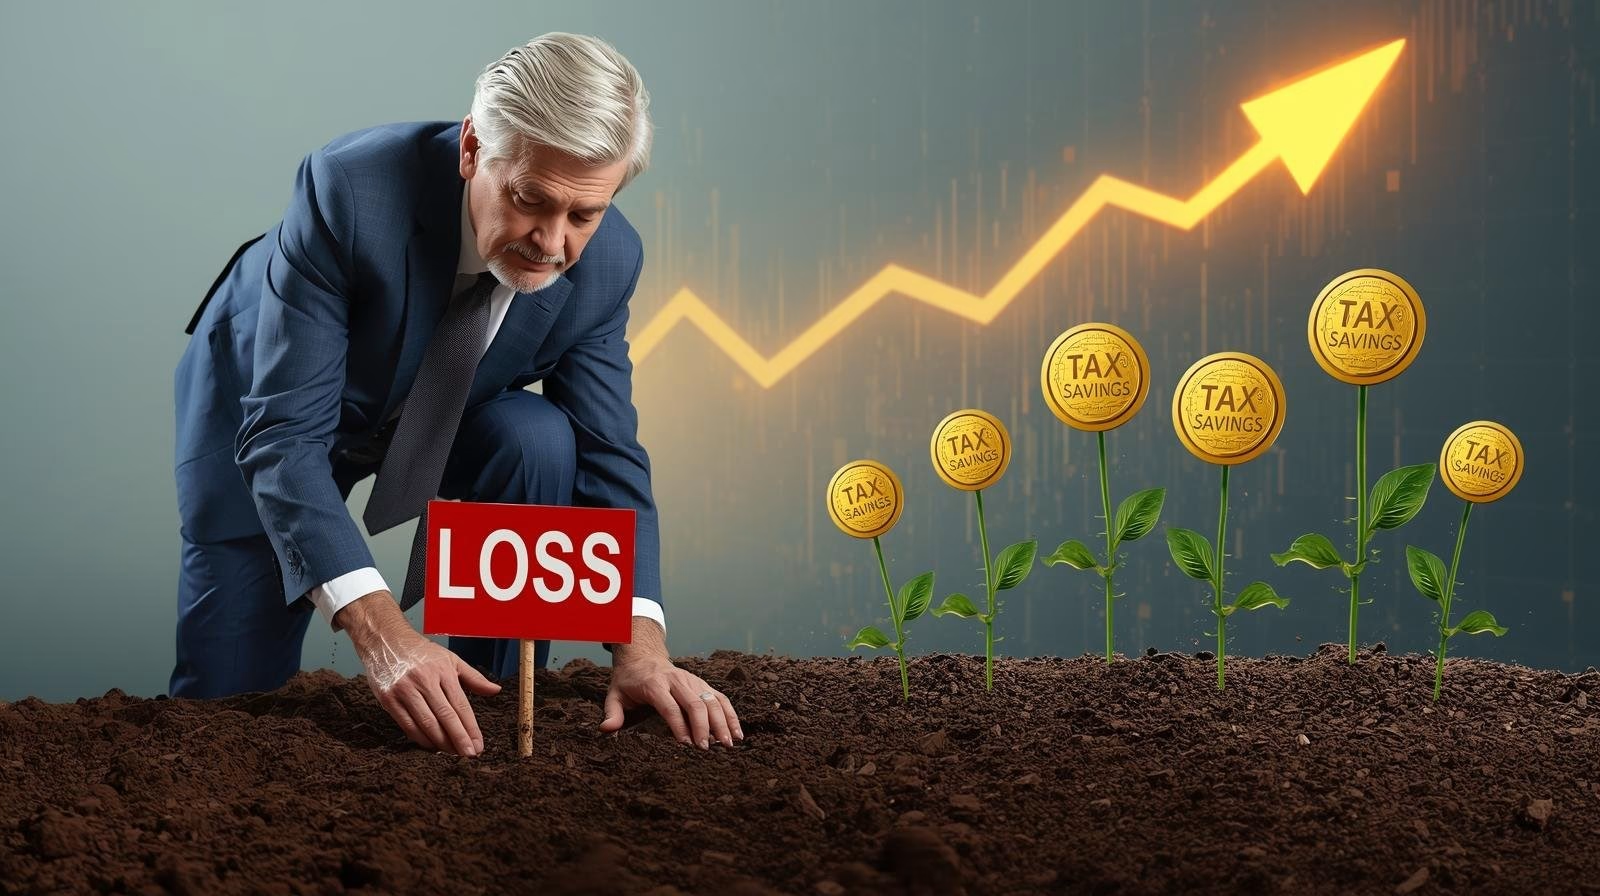
Most investors think about what they own. Tax-loss harvesting is about what you own, what you sold, and when you sold it — because a realized loss in a taxable account is a real-money deduction, not just a paper setback.
The mechanics are straightforward: you sell an investment that has dropped below your purchase price, realize a capital loss, and use that loss to cancel out capital gains elsewhere in your portfolio. Done at year-end, or opportunistically throughout the year, tax-loss harvesting for long-term savings can meaningfully reduce the tax you owe — while keeping your portfolio's overall market exposure essentially unchanged. That last part is the key: the goal is not to abandon the market, but to capture the tax value of a temporary decline and reinvest in a similar but not identical position.
How Tax-Loss Harvesting Actually Works
Every dollar of capital loss you realize offsets a dollar of capital gain. Long-term losses (positions held more than one year) first offset long-term gains, and short-term losses first offset short-term gains. When losses exceed gains in a category, they cross over to reduce the other type.
If total capital losses still exceed total capital gains after all netting, the IRS allows you to deduct up to $3,000 of net capital losses against ordinary income per year ($1,500 if married filing separately). This figure is confirmed in IRS Topic 409, Capital Gains and Losses, last updated February 2026. Any unused losses beyond $3,000 carry forward to the next tax year indefinitely — they do not expire after a set number of years.
The financial benefit depends on your bracket. For 2025, the long-term capital gains rates are 0%, 15%, or 20% depending on taxable income (current thresholds available at IRS.gov/taxtopics/tc409). For someone in the 15% capital gains bracket, a $10,000 realized loss that offsets $10,000 of gains translates to $1,500 in actual tax savings. For someone in the 20% bracket with the additional 3.8% net investment income tax, the same loss saves $2,380.
A common misconception is that tax-loss harvesting eliminates tax permanently. It doesn't — it defers it. When you sell the replacement security later, your lower cost basis generates a larger gain. But the deferral itself has real value: the money not paid to the IRS this year continues to compound in the portfolio, and the future gain may be taxed at a lower rate (particularly if it falls in a lower-income year, or if the assets are held until death and receive a stepped-up basis).
The Wash-Sale Rule: The Binding Constraint
Tax-loss harvesting for long-term savings has one firm limitation: the wash-sale rule under IRC Section 1091. If you sell a security at a loss and buy a "substantially identical" security within 30 calendar days before or after the sale, the IRS disallows the loss entirely. The disallowed loss is added to the cost basis of the replacement security — it shifts to a future year, not permanently eliminated.
"Substantially identical" means the same stock, the same bond, the same mutual fund, or funds from the same family tracking the exact same index. Selling one S&P 500 index fund and buying a different S&P 500 index fund from another provider is generally considered a wash sale because both track the same underlying index.
The replacement strategy for avoiding wash sales while maintaining market exposure is to use securities that are similar but legally distinguishable:
- Replace an S&P 500 ETF with a total U.S. market ETF (which holds the same stocks plus smaller companies)
- Replace a large-cap growth fund with a different large-cap growth ETF from a different provider tracking a different index
- Replace a bond fund tracking one benchmark with a bond fund tracking a comparable but distinct benchmark
This keeps the portfolio invested in similar asset classes without triggering the rule. The 30-day window runs in both directions from the sale date — if you buy a substantially identical replacement more than 30 days before you sell the loser, you also violate the wash-sale rule on those purchased shares.
One important note for those who own mutual funds in employer accounts: if you hold shares of a substantially identical fund in a 401(k) and you sell shares at a loss in a taxable brokerage account, the IRS may consider that a wash sale even across account types. Coordinate purchases across all your accounts, not just within a single brokerage.
ETFs vs. Mutual Funds for Harvesting
Exchange-traded funds have made tax-loss harvesting considerably more practical for individual investors compared to traditional actively managed mutual funds, for several reasons.
First, ETFs trade throughout the day at market prices. When volatility spikes intraday — which is exactly when large paper losses create harvesting opportunities — you can act on a specific price. Mutual funds price once per day at the closing net asset value, which can mean missing a low point during an intraday selloff.
Second, the ecosystem of low-cost index ETFs from competing fund families offers plenty of similar-but-not-identical replacement candidates. Vanguard, iShares, Schwab, and State Street each offer broad domestic market ETFs tracking different underlying indexes, providing legitimate wash-sale-compliant substitutes without meaningfully altering portfolio exposure.
Third, index ETFs in taxable accounts tend to generate fewer internal capital gain distributions than actively managed funds. Actively managed funds that turn over holdings frequently distribute gains annually — increasing the tax drag from the fund itself. Index ETFs in contrast rarely trigger distributions, making them cleaner vehicles for taxable accounts over long holding periods.
Finally, the specific lot tracking available in most modern brokerage platforms lets ETF holders choose which lots to sell — maximizing the harvested loss by selecting the highest-cost-basis lots when selling, or the lowest-cost-basis lots when selling a position entirely.
Robo-Advisors and Automated Harvesting
Several automated investment platforms now offer daily or continuous tax-loss harvesting, compared to the typical individual investor's once-per-year December review.
The mechanical advantage: automated systems monitor positions daily and sell when losses exceed a threshold, then reinvest immediately in the wash-sale-compliant substitute. Operating continuously rather than at year-end means capturing losses during mid-year corrections that recover before any manual year-end review would catch them.
The structural context: robo-advisors with automated harvesting typically hold ETF pairs — for example, a primary S&P 500 ETF and a substitute total-market ETF — and alternate between them when harvesting. The portfolio is never out of the market for more than the transaction settlement period.
The important caveat: the long-term value of automated daily harvesting vs. occasional manual harvesting is disputed in financial research. More frequent harvesting generates more deferred gains embedded in lower-basis positions, which eventually realize in a tax event. For investors who hold for many decades or pass assets to heirs with a stepped-up basis, the compounded deferral closely approximates a permanent benefit. For investors who liquidate within a few years, the benefit is less.
Short-Term vs. Long-Term: Which Loss Is More Valuable?
The IRS netting sequence for capital gains and losses has a specific order that affects the economic value of different loss types.
Short-term losses first offset short-term gains. Long-term losses first offset long-term gains. After within-category netting, cross-category netting occurs.
Short-term gains (from positions held one year or less) are taxed as ordinary income at marginal rates that can reach 37% for high earners. Long-term gains face a maximum of 20% (plus 3.8% net investment income tax for incomes above specific thresholds, per IRS Topic 559). A short-term loss is therefore more valuable than a long-term loss when it offsets a short-term gain, because it shields income taxed at a higher rate.
When you have both types of losses available in a portfolio, understanding this netting sequence helps prioritize which positions to harvest first. If your portfolio has both short-term and long-term gains, and you have both types of losses, harvest short-term losses first — they create the largest tax reduction per dollar of loss.
One counterpoint: a position that has been held 11 months and is at a loss has a short-term loss right now. Holding another 35 days converts it to a long-term position. If you expect the loss to persist or worsen, it may be worth waiting for the long-term designation if the math favors that — particularly if you have more long-term gains than short-term gains to offset.
The $3,000 Ordinary Income Offset in Detail
The $3,000 ordinary income offset is the part of tax-loss harvesting that most surprises investors who learn about it for the first time.
After all capital gains and losses are netted, if you end up with a net capital loss, up to $3,000 of that loss reduces your ordinary income — your wages, self-employment income, interest, or other earnings taxed at marginal bracket rates. If your marginal income tax rate is 32%, a $3,000 deduction saves $960 in federal income tax. At a 24% rate, it saves $720.
This $3,000 figure has not been indexed for inflation since 1978, when it was established at its current level. Proposals to increase it have appeared in various legislative discussions without passage. The carry-forward feature is the primary compensating mechanism: losses harvested in a large-loss year carry forward indefinitely.
For investors who experienced significant portfolio losses in a market downturn — say, harvesting $50,000 in losses in a year with minimal gains — the carry-forward position becomes a multi-year asset. With $3,000 applied against ordinary income each year, the remaining carry-forward continues to offset any future capital gains realized in subsequent years. A $50,000 loss position, if not fully utilized against future gains, takes more than 16 years to exhaust at $3,000 per year — but most investors generate some capital gains along the way that consume the carry-forward faster.
Harvesting in Practice: A Year-End Process
The mechanics involve several steps in sequence.
Review all taxable accounts for unrealized losses. Focus on positions where the current market value is materially below your adjusted cost basis. If you've held a position through multiple purchases, each lot may have a different basis and holding period — use your brokerage's tax-lot accounting to identify which specific lots are at a loss.
Identify wash-sale-compliant replacements before selling. Know what you will buy before you sell. The 30-day window begins on the sale date, so the replacement must be selected and purchased on the same day or within 30 days.
Check the holding period. A position held 364 days has a short-term loss. Holding 1 more day converts it to a long-term position — which may be more or less valuable depending on what types of gains you need to offset.
Account for transaction costs and bid-ask spreads. In a well-run taxable account holding low-cost index ETFs, these are typically negligible. In accounts with high-commission structures or illiquid positions, the frictional costs can offset a portion of the tax benefit.
Coordinate with mutual fund distributions. Many equity mutual funds distribute capital gains in November and December. If you plan to sell a fund shortly after a large distribution, you may have to include that gain on your return regardless — plan around the distribution calendar.
Document the substitution. Record which positions you sold and what you bought as replacements, including dates and prices. This documentation supports your tax return if the IRS questions whether the replacement was substantially identical.
When Tax-Loss Harvesting Makes Less Sense
The strategy is not universally valuable. Several situations reduce or eliminate the benefit.
Low-bracket investors. If your taxable income falls in the 0% capital gains bracket (single filers below $48,350 in taxable income in 2025, per IRS Topic 409), long-term capital gains already owe no federal tax. Harvesting a loss to offset a gain you owe nothing on generates no immediate savings — only a lower cost basis in the replacement.
Tax-deferred and tax-free accounts. Losses in IRAs, Roth IRAs, and 401(k)s have no tax consequence. Only taxable brokerage accounts contain positions where loss harvesting produces a deductible result.
High turnover and basis complexity. If tax-loss harvesting generates constant position swaps, tracking cost basis across many lots across multiple accounts becomes error-prone. The administrative burden and risk of basis errors should factor into how aggressively you harvest.
Very short planned holding periods. If you expect to sell an investment for any reason within one to two years regardless of price, the deferral value of harvesting now is small.
The IRS provides the full treatment of capital gains and losses in Publication 550 and in the Schedule D instructions, both available at IRS.gov.
For the IRS-verified source on capital gains rates and the $3,000 loss limit: https://www.irs.gov/taxtopics/tc409
None of this is financial advice. Your situation depends on variables this article can't see — taxes, risk tolerance, time horizon, dependents. A fiduciary advisor can model your specific case.

No comments yet